
M&A & ESOP Advisory for Business Services Companies
ButcherJoseph & Co. advises owners of business services companies through ownership transitions — including ESOP buyouts, sell-side M&A, and capital advisory — with a focus on protecting the intangible assets that drive value in this sector. In services businesses, those assets walk out the door every evening, which makes the structure of a deal matter as much as the price.
What Business Services M&A Advisory Involves
Business services M&A advisory is the process of structuring, marketing, and executing an ownership change for a services-oriented company — staffing firms, outsourced business process providers, consulting practices, facilities management companies, professional employer organizations, and similar businesses where recurring client relationships and human capital are the primary assets.
What separates a well-executed transaction from a value-destroying one in this sector is the advisor’s understanding that financial buyers underwrite these deals differently than they would a manufacturer. Customer concentration thresholds, contract duration, key-person dependencies, and revenue quality metrics all receive intense scrutiny in due diligence. We work with owners well before a transaction to identify and remediate those exposure points, structure deals that reflect actual enterprise value, and source capital from lenders and investors who already understand the sector’s cash flow characteristics.
Owners Who Fit This Profile
Business services owners pursue transactions for specific reasons that don’t always fit a generic sell-your-business narrative. Common triggering scenarios:
How Our Business Services M&A Process Works
Serving this sector well requires a process built around the specific diligence triggers that buyers and lenders will surface. Our advisory engagement moves through five stages:
Feasibility & Positioning
We assess your business against current buyer appetite and market comparables, identify value drivers and risks, and establish a realistic range of outcomes before any marketing begins. This is where we surface customer concentration issues, key-person dependencies, and contract structures that will influence pricing.
Transaction structure
Whether the right answer is an ESOP, a third-party sale, a management buyout, or a combination of these, we design the structure around your priorities — liquidity, taxes, continuity, and team retention — before approaching any counterparty.
Capital sourcing
We access a proprietary network of lenders and equity sponsors who finance business services transactions regularly. Securing the right capital stack at terms that support the deal structure is often the most complex step, particularly in asset-light businesses where senior lenders require strong recurring revenue as collateral.
Negotiation and due diligence management
We run the process: managing buyer or lender diligence, negotiating representations and warranties, and coordinating legal, accounting, and HR work streams so you can continue running the business.
Closing and transition
We stay engaged through close and into the transition period, particularly in ESOP transactions where trustee requirements and employee communication plans are part of a successful handoff.
Ready to Know What Your Business Is Worth?
Request a confidential feasibility review — no obligation, no public disclosure.
Key Considerations in Business Services Transactions
How is a business services company valued?
Business services companies are typically valued on an EBITDA multiple basis, adjusted for revenue quality, customer concentration, contract duration, and key-person risk. Recurring, contracted revenue commands higher multiples than project-based revenue. Buyers and lenders also scrutinize client tenure and gross margin by service line, since these metrics reveal how defensible the earnings base actually is.
How are these deals financed?
Most business services transactions use a combination of senior debt, seller notes, and equity. Because these businesses carry few hard assets, senior lenders focus on recurring cash flow and contract stability as the primary underwriting criteria. ESOP transactions typically rely on a blend of senior and subordinated debt, sized to the company’s debt service capacity. Leverage levels vary by revenue quality and business model.
Can I sell part of my business and stay involved?
A partial transaction — ESOP recapitalization, minority equity sale, or management buyout with retained equity — is often the right structure for business services owners who are not ready for a clean exit. These structures allow you to diversify personal wealth, retain operational involvement, and participate in future value creation. We design partial transactions regularly and can walk through the scenarios specific to your situation.
What are the tax implications for a business services seller?
Tax treatment depends on entity structure, deal structure, and state of domicile. Under certain circumstances, S-corporation ESOP transactions provide substantial corporate tax benefits that can result in little to no federal income tax paid by the company, while C-corporation selling shareholders may defer capital gain taxes under IRC Section 1042 subject to eligibility and reinvestment requirements. Installment sale treatment may apply to seller notes. Tax outcomes are deal-specific and require coordination with qualified tax counsel — we work with experienced advisors in our network to model the after-tax economics of each structure before a decision is made.
Selected M&A & ESOP Transactions
Employee ownership transactions we have advised across construction, industrial, distribution, healthcare and business services.




A Recent Employee Ownership Transaction
AMPAM Parks Mechanical
The largest multifamily plumbing contractor in the United States, with more than $1 billion in completed contracts, sold 100% of the company to an ESOP. We structured the transaction, negotiated liquidity for the selling shareholders and arranged the financing.
“This transaction enables our employees to partner in the growth and future of the company that they helped build.”Charles “Buddy” Parks, Chairman
“ButcherJoseph's expertise and strategic insight were instrumental in helping us structure a deal that truly puts our people first.”
Direct Advice From Experienced ESOP Bankers
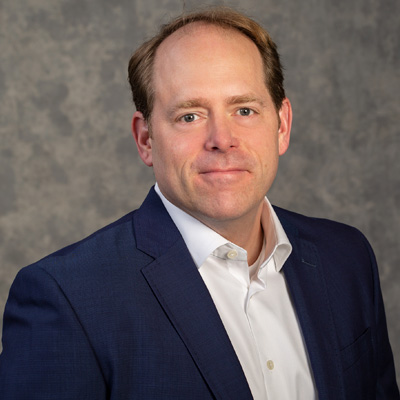
Keith Butcher, Managing Partner, co-founded ButcherJoseph in 2011 and has advised on more than 150 transactions as an investment banker and attorney, including ESOP-focused employee benefits law before joining Morgan Stanley.
The banker you meet in the first conversation is the banker who runs your transaction. We do not hand engagements to a junior team once the agreement is signed.
FAQs — Business Services M&A Advisor
What size company is a candidate for an ESOP or M&A transaction?
Most ESOP candidates have at least $3M in EBITDA and 30 or more employees, with annual revenue of $20M and up being a typical range for business services companies, though larger and more complex transactions are common in our practice. ESOP feasibility typically requires sufficient sustainable cash flow to service acquisition debt and a strong management team — we assess this during an initial feasibility review, which is confidential and carries no obligation.
How long does a business services M&A or ESOP transaction take?
Most transactions close within six to twelve months from engagement. ESOP transactions often run toward the longer end of that range due to trustee review, independent valuation requirements, and financing syndication. Third-party sell-side processes can move faster when the business is well-prepared before marketing begins.
How is a business services company valued for an ESOP or sale?
Valuation is based on a multiple of EBITDA, adjusted for revenue concentration, contract quality, and key-person risk. A certified independent valuation is required in ESOP transactions. For third-party sales, market comparables and buyer-specific synergies also influence final pricing.
Can a business services company with significant customer concentration complete a transaction?
Concentration is manageable, not disqualifying. Buyers and lenders price concentration risk into structure — higher equity requirements, earnout provisions, or seller note sizing. We work with owners to address concentration before going to market where possible, which protects both valuation and deal certainty.
Is an ESOP a good exit strategy for a business services company?
An ESOP is particularly well-suited to business services firms because the workforce is the primary asset. Employee ownership can strengthen retention, preserve culture, and maintain client relationships through a transition — outcomes that matter especially in people-dependent businesses. Whether an ESOP is the right structure depends on your liquidity goals, timeline, and debt capacity.
How do I choose the right M&A advisor for a business services transaction?
Look for an advisor with demonstrated experience in asset-light, people-intensive businesses — not just general M&A credentials. The advisor should understand how lenders underwrite services cash flows and have relationships with capital providers active in this sector. With over $30 billion in M&A transactions and $10 billion in ESOP transactions completed across over 200 firm transactions, we bring both pattern recognition and an established capital network to every engagement. Ask for examples of comparable transactions and ask specifically how they handle customer concentration and key-person risk in positioning.
Schedule a Confidential Discussion
Talk to an advisor who knows this sector. Start your confidential feasibility review today.